“10 Financing Options for Building or Buying a Tiny House on a Budget”
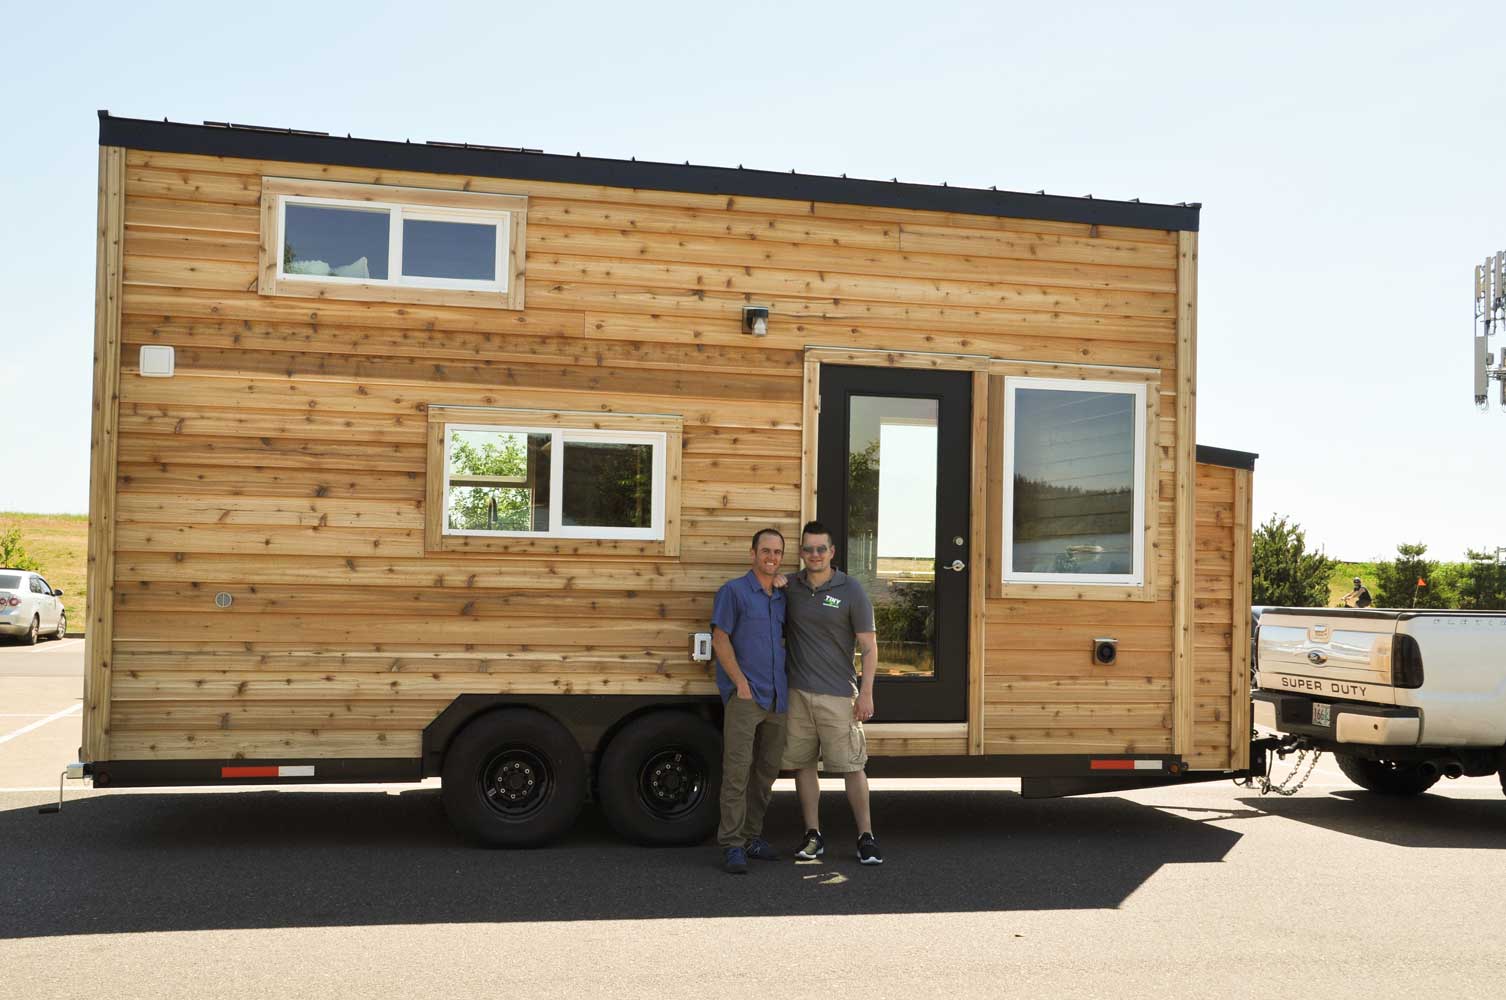
Financing Options for Building or Buying a Tiny House on a Budget
Tiny houses have become increasingly popular in recent years, offering an affordable and sustainable housing solution for those looking to downsize or live more simply. Whether you plan to build your own tiny house or purchase one that’s already built, finding the right financing options can make all the difference. In this article, we will explore various financing options available to help you finance your dream of owning a tiny house on a budget.
1. Personal Savings: One of the simplest and most common ways people finance their tiny homes is by using personal savings. If you’ve been diligently saving money over time, this could be an excellent option for you. Using personal savings means no monthly payments or interest charges, giving you complete ownership from day one.
2. Traditional Mortgage Loans: Although traditional mortgages are typically associated with larger homes, some financial institutions offer mortgage loans specifically tailored to tiny houses. These loans often have shorter terms and may require higher down payments compared to conventional home mortgages.
3. RV Loans: Since many tiny houses are classified as recreational vehicles (RVs), qualifying for an RV loan might be easier than obtaining a traditional mortgage loan. RV loans generally have lower interest rates and longer repayment periods than personal loans but may require proof of compliance with certain safety standards.
4. Personal Loans: Many lenders offer unsecured personal loans that can be used for various purposes, including financing a tiny house purchase or construction project. These loans usually have fixed interest rates and repayment terms ranging from three to seven years depending on the lender.
5. Credit Cards: While not typically recommended due to high-interest rates, credit cards can provide short-term funding solutions if used responsibly and paid off quickly after making the initial purchase or covering construction costs.
6. Crowdfunding: If you’re passionate about your tiny house project and believe others would support it too, crowdfunding could be an interesting option worth exploring. Platforms like Kickstarter or GoFundMe allow you to share your story and raise funds from individuals who are interested in supporting your dream of owning a tiny house.
7. Owner Financing: In some cases, the seller of a pre-built tiny house may be willing to offer owner financing. This means that instead of going through a traditional lender, you make monthly payments directly to the seller until the full amount is paid off. This option can be flexible and more accessible for those with limited credit history or lower credit scores.
8. Community Development Financial Institutions (CDFIs): CDFIs are specialized financial institutions that focus on providing affordable lending options in underserved communities. Some CDFIs offer loan programs specifically designed for alternative housing solutions such as tiny houses.
9. Home Equity Line of Credit (HELOC): If you already own a property with equity, a HELOC might be an option worth considering. A HELOC allows you to borrow against the equity in your existing home and use those funds towards purchasing or building a tiny house.
10. Grants and Foundations: While not common, there are grants and foundations available that support sustainable housing initiatives, including tiny houses. These grants often have specific eligibility requirements, so thorough research is necessary to find ones that align with your goals.
Before settling on any financing option, it’s crucial to do thorough research and consider all factors involved – interest rates, repayment terms, down payment requirements, eligibility criteria, etc. Additionally, budgeting carefully for ongoing expenses such as insurance, taxes if applicable based on local regulations or land ownership arrangements should also be considered when determining affordability.
Building or buying a tiny house on a budget requires careful planning and consideration of various financing options available today. By exploring these alternatives mentioned above and selecting the one that best suits your needs and financial situation while keeping long-term sustainability in mind; you’ll be one step closer to achieving your dream of living luxuriously within your means.